Tesla Financial Model financial model
This Excel financial model of Tesla Financial Model was built automatically by Skale from 7 published documents. It is a 3-statement model (income statement, balance sheet, cash flow) with 5 projected years, Sep-27E to Sep-31E, across six sheets, and includes a DCF valuation. For LTM Sep-26 it shows revenue of $103.6 billion, net income to shareholders of $3.2 billion and net cash of $8.3 billion; the DCF gives an enterprise value of $10.2 billion and a value per share of $13.15 under the model's assumptions.
Preview the Excel
The first rows of each sheet, as they open in Excel.
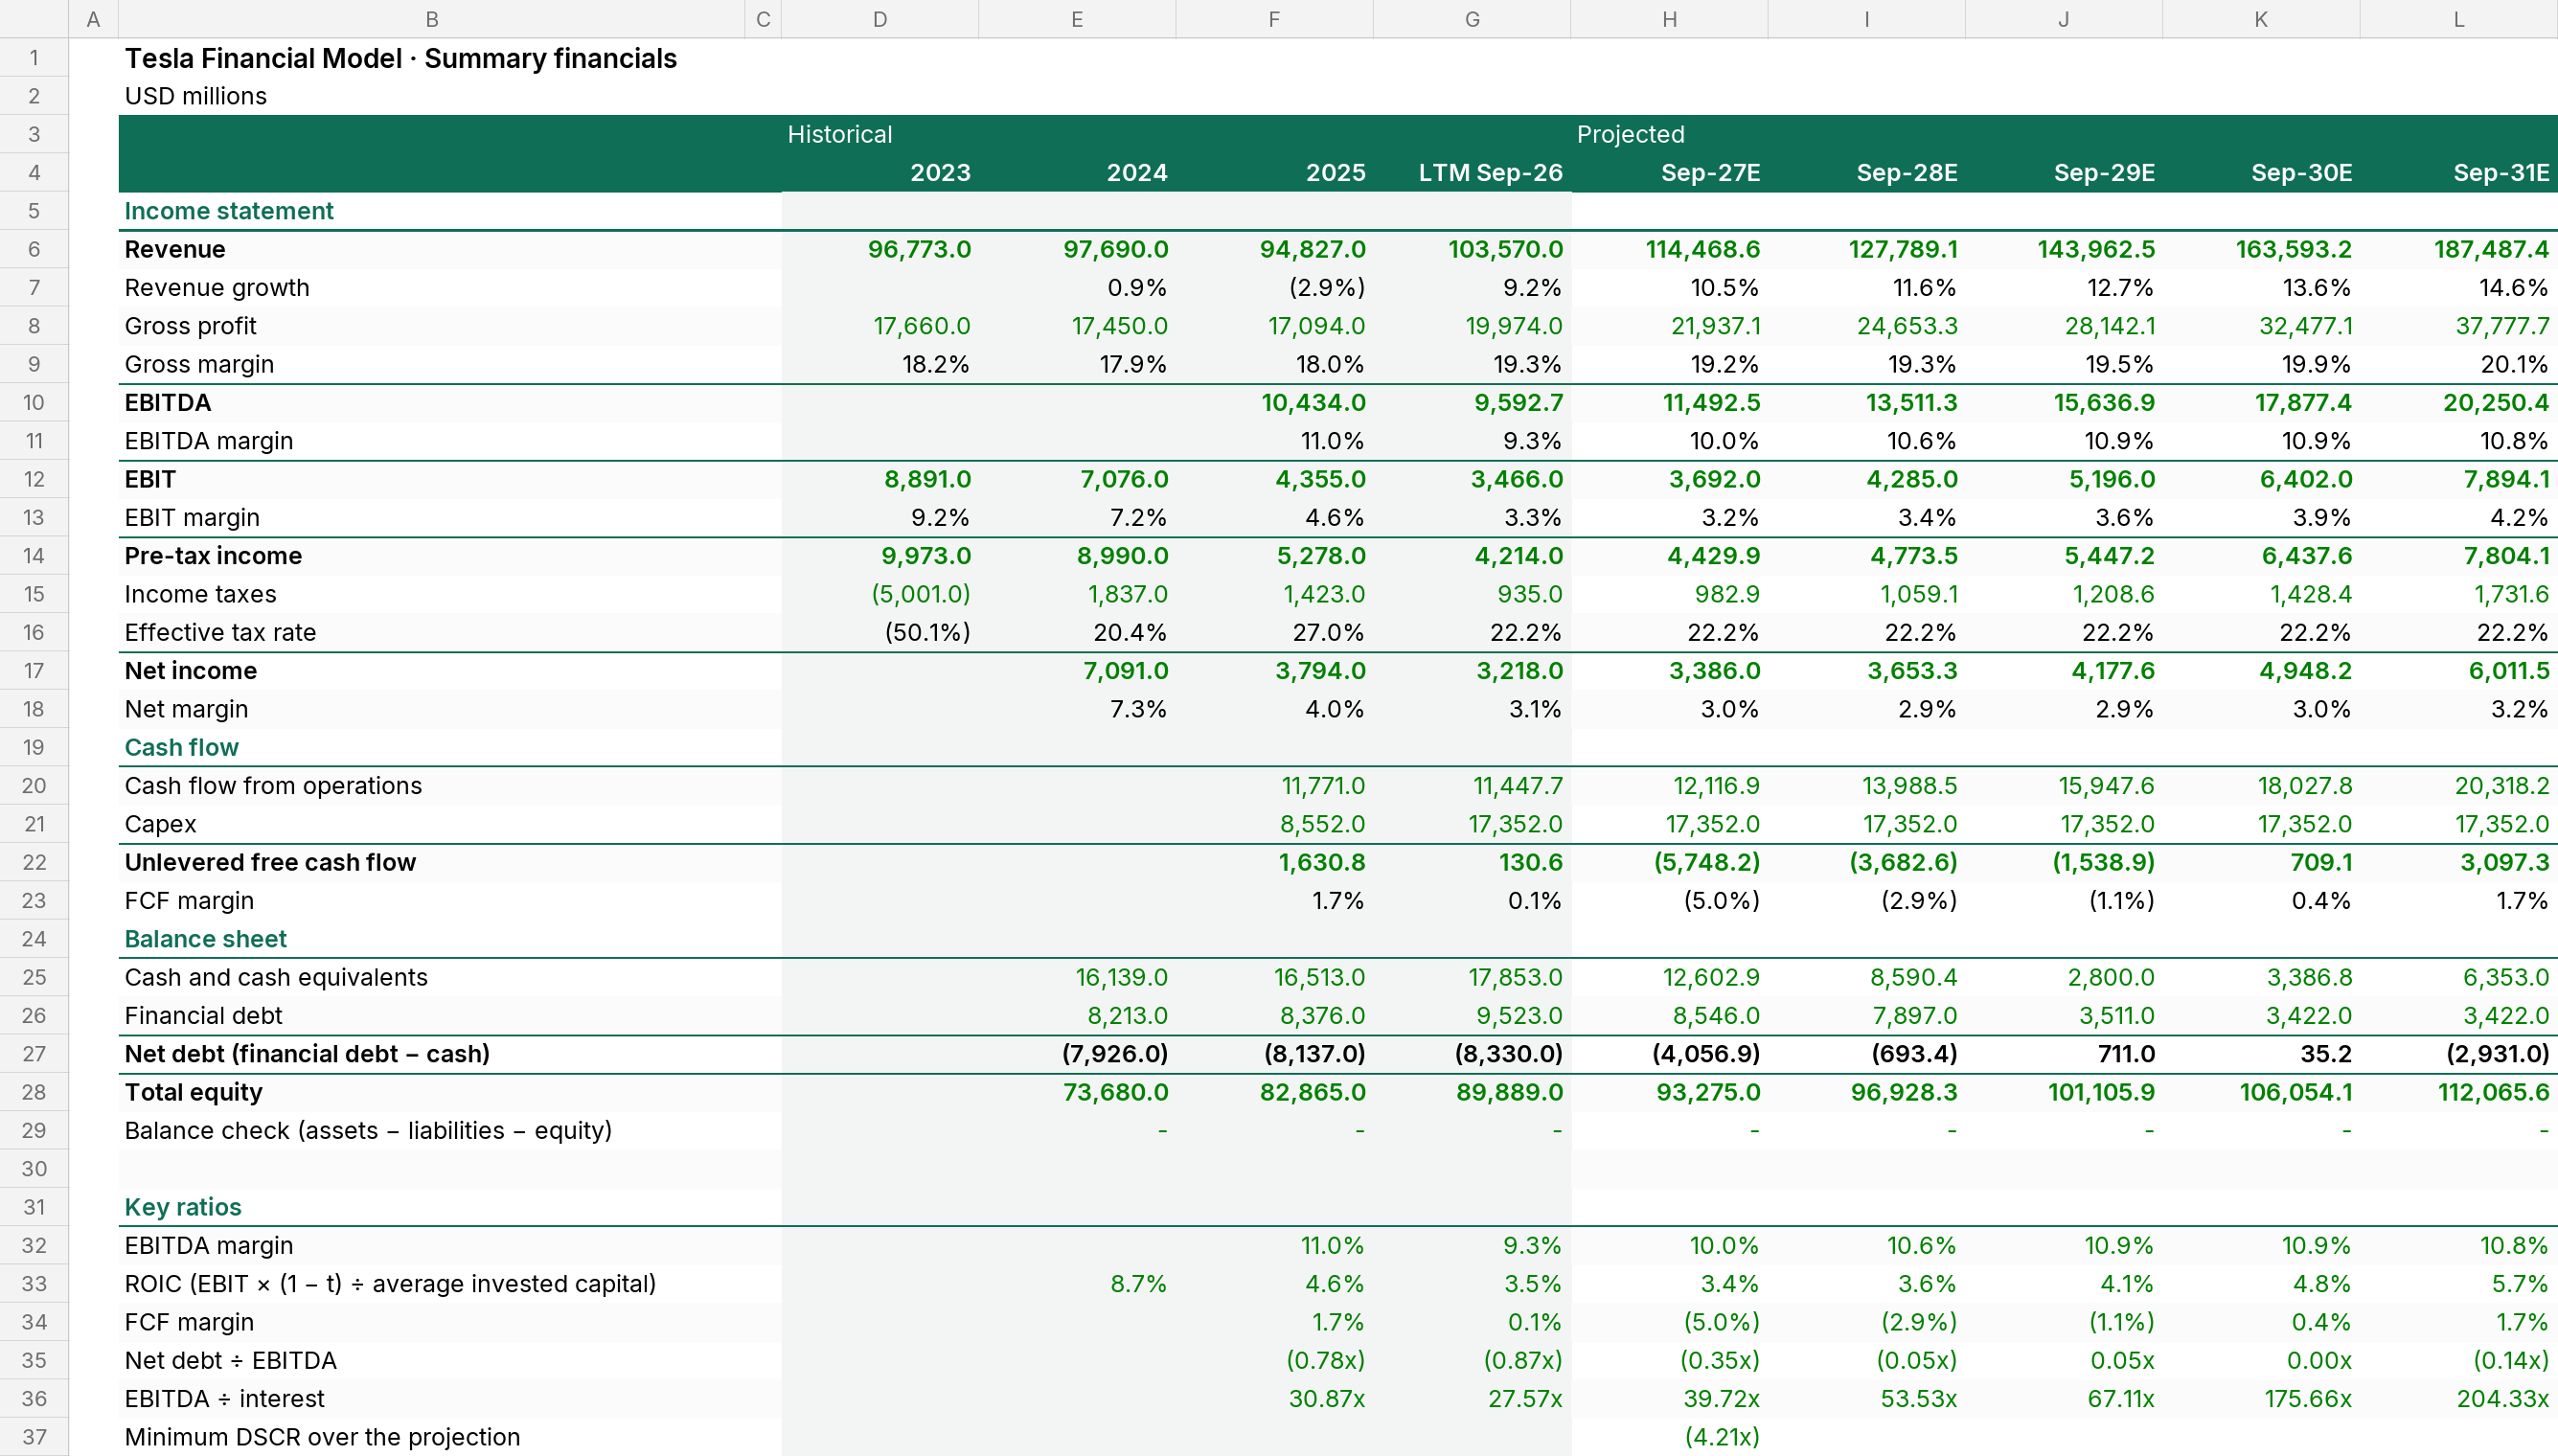
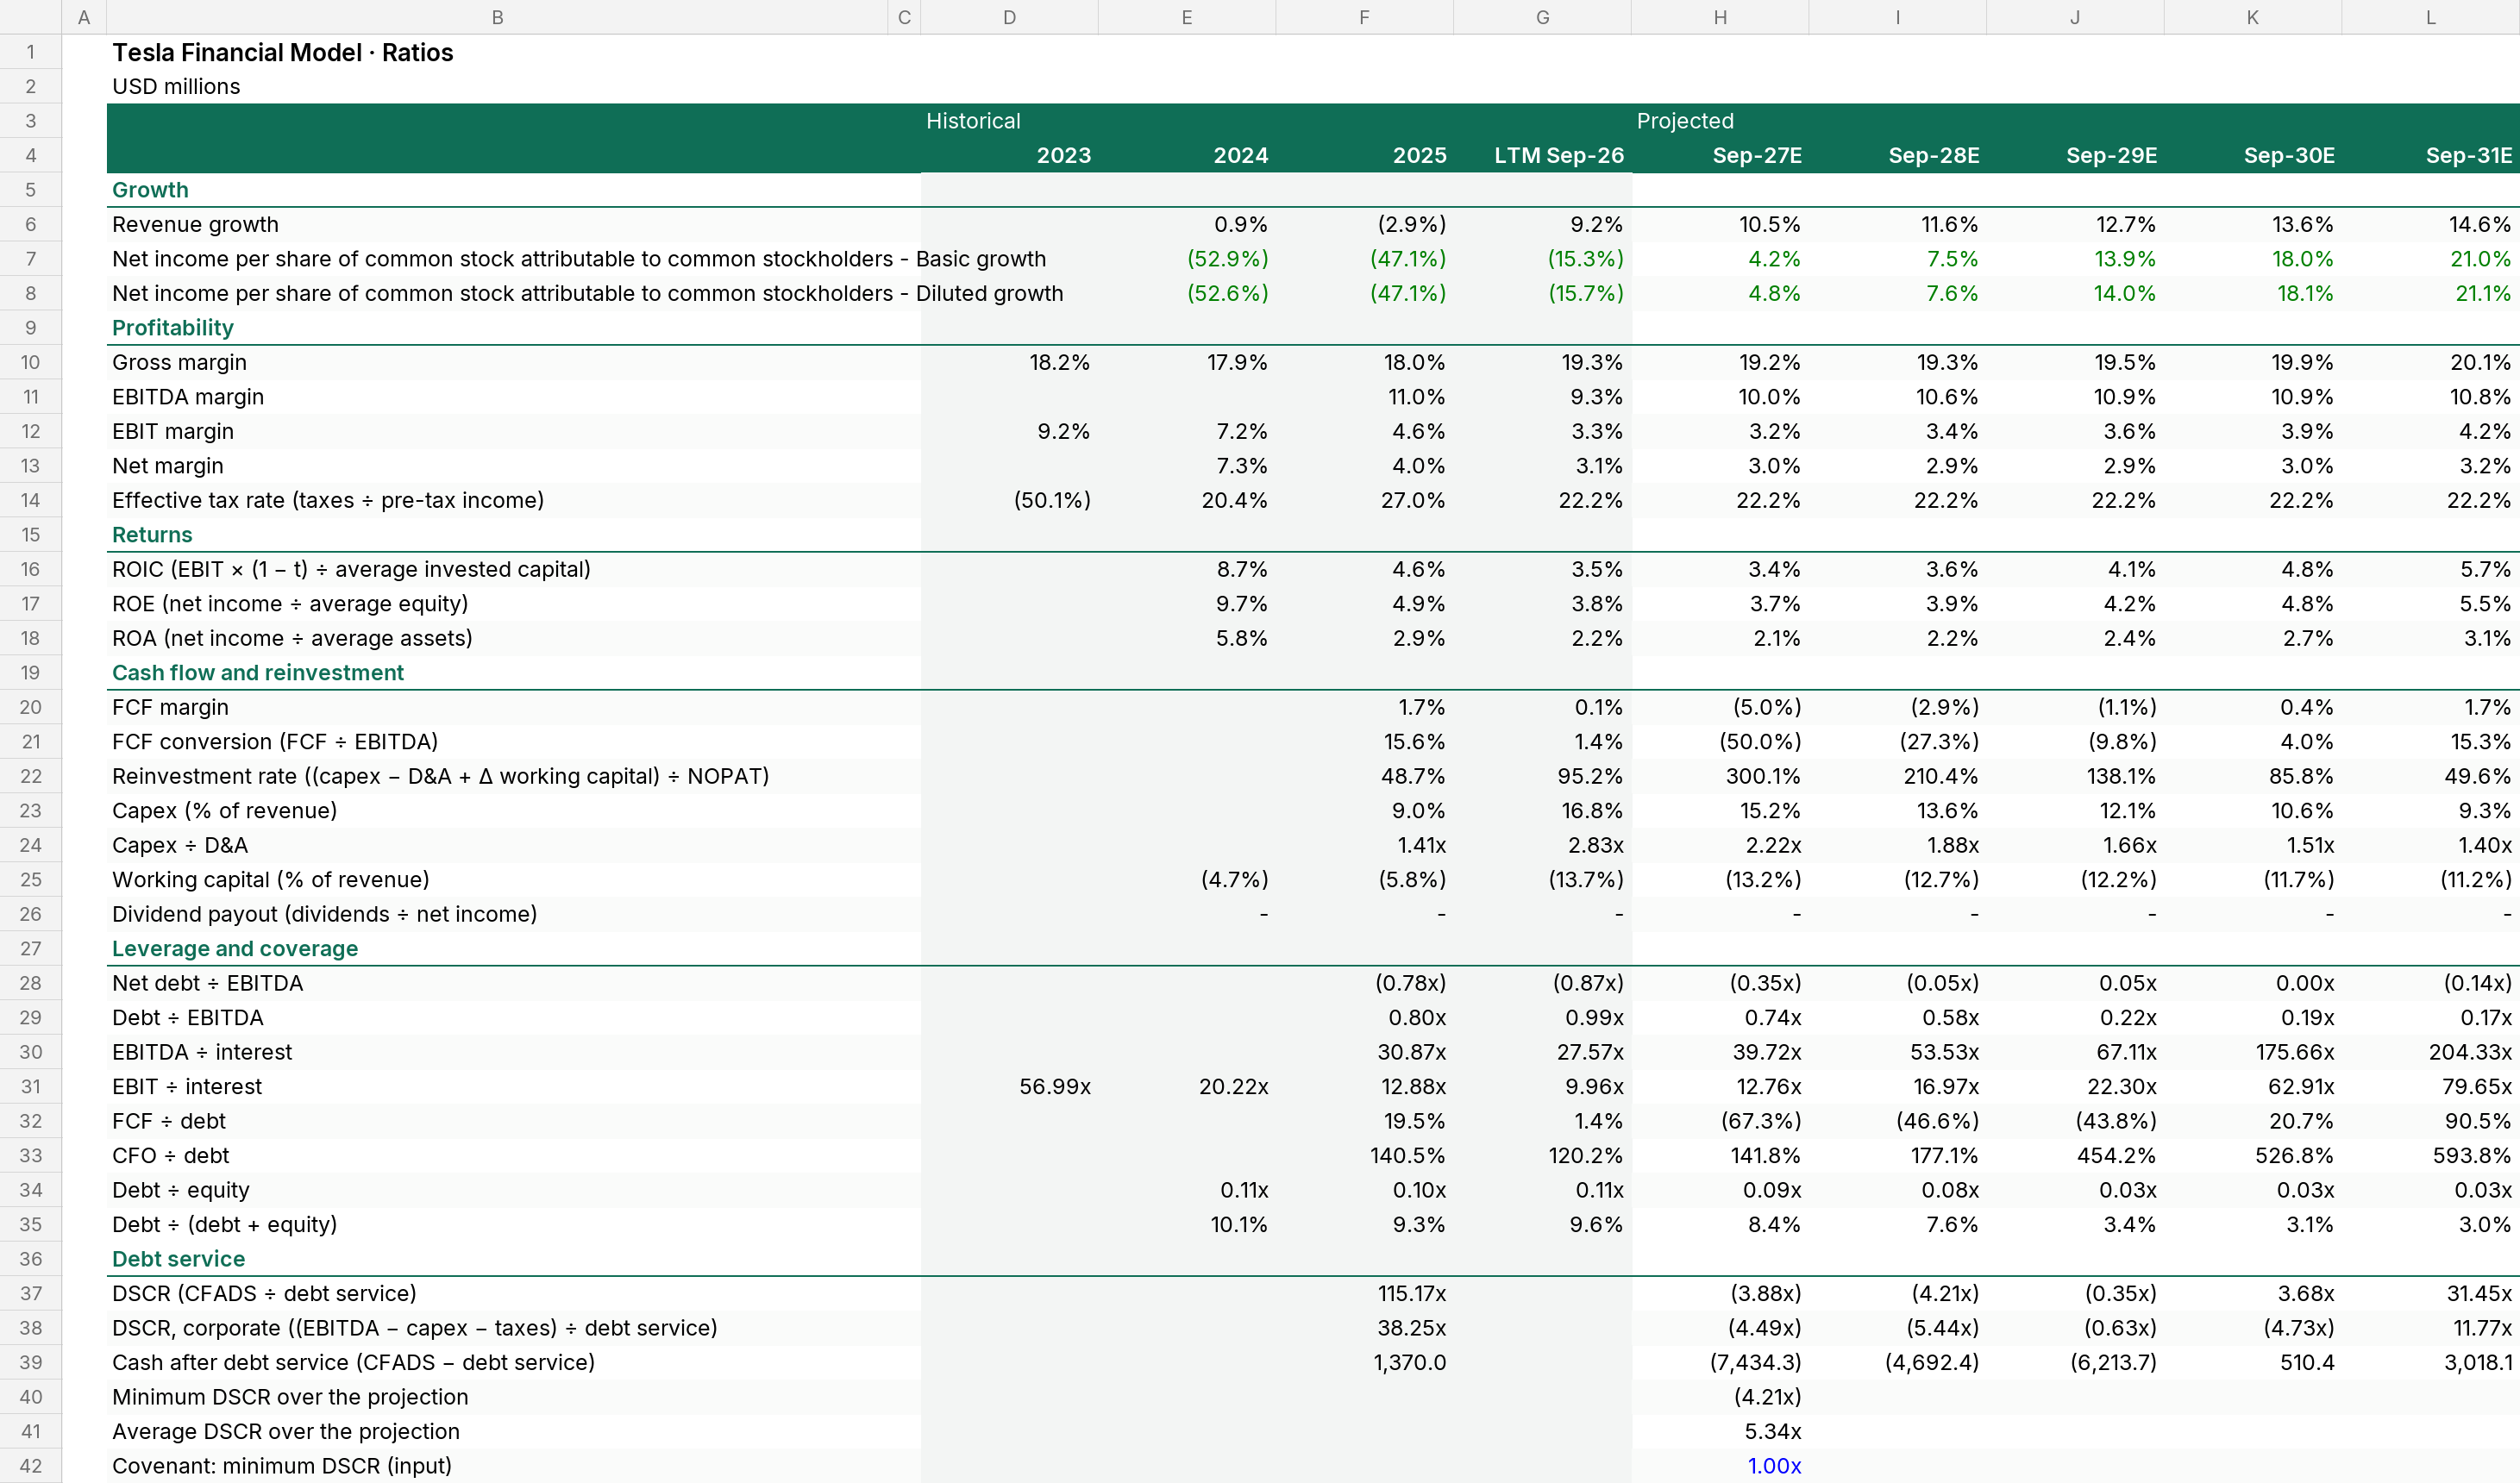
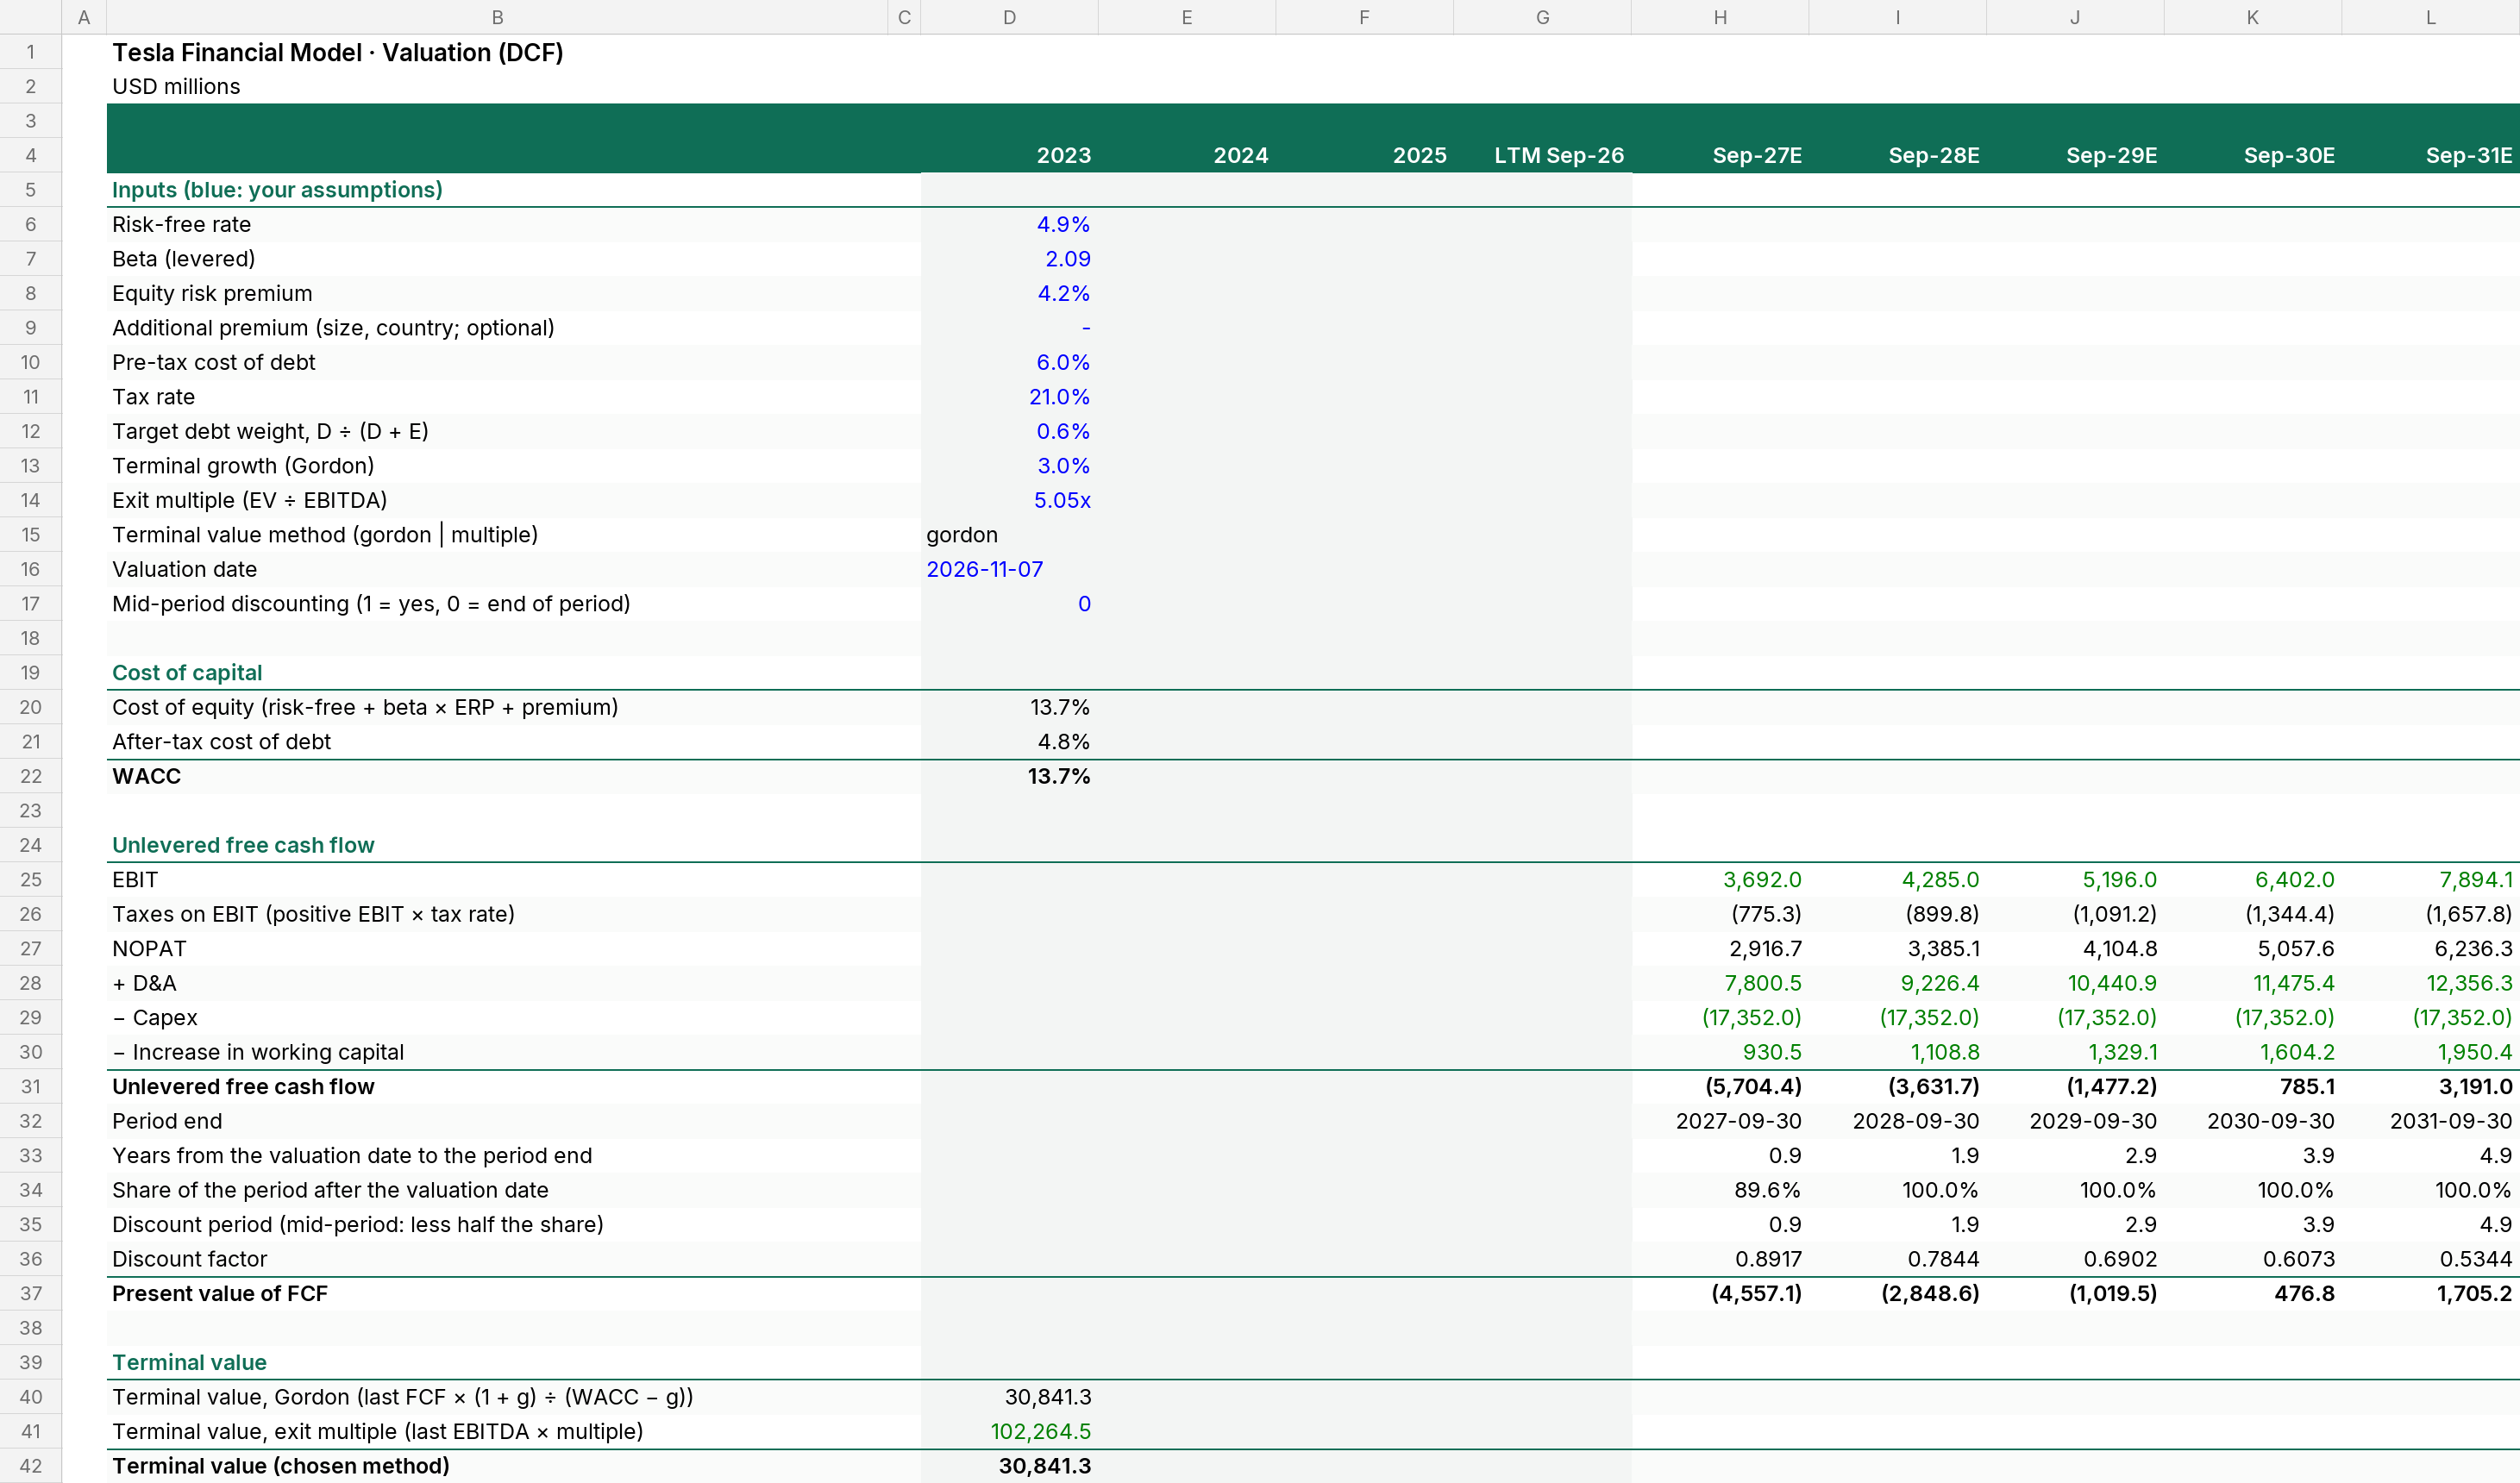
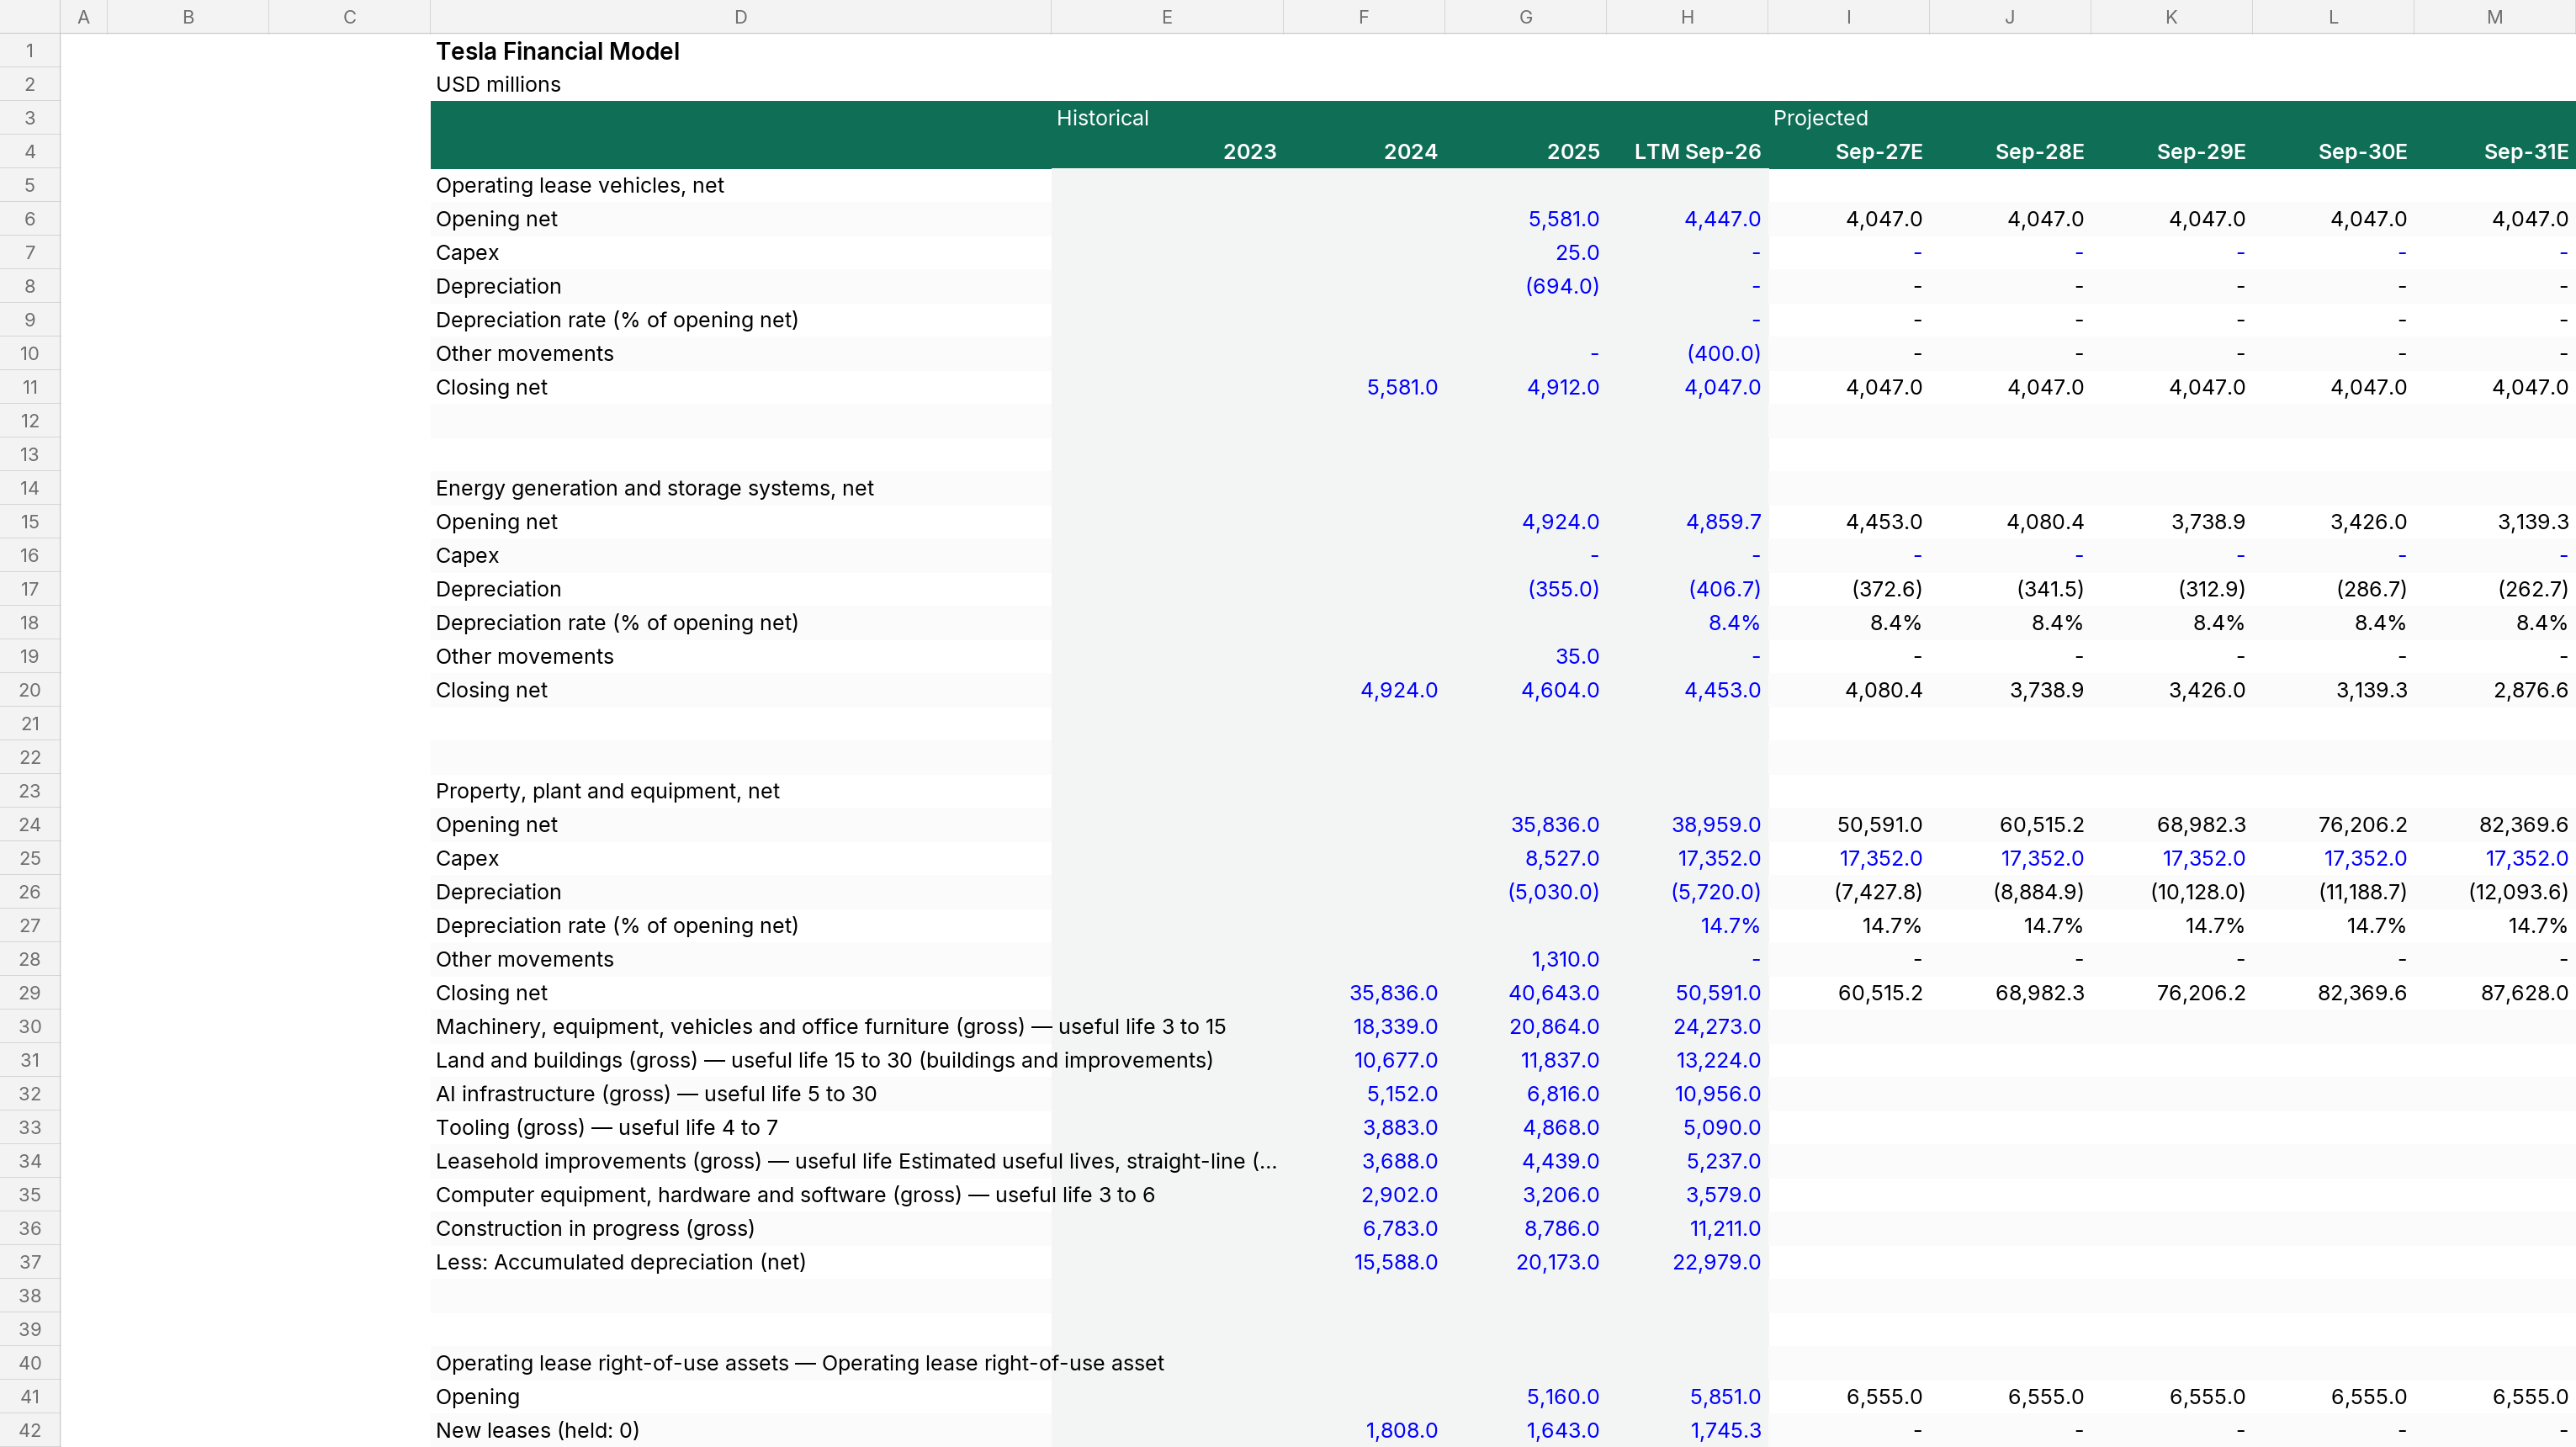
Tesla Financial Model summary financials
USD millions · historical and projected years 2023–2031. From the model's Summary sheet; every projected figure is a formula in the Excel.
| Historical | Projected | |||||||||
|---|---|---|---|---|---|---|---|---|---|---|
| USD millions | Unit | 2023 | 2024 | 2025 | 2026 | 2027E | 2028E | 2029E | 2030E | 2031E |
| Income statement | ||||||||||
| Revenue | 96,773.0 | 97,690.0 | 94,827.0 | 103,570.0 | 114,468.6 | 127,789.1 | 143,962.5 | 163,593.2 | 187,487.4 | |
| Revenue growth | 0.9% | (2.9%) | 9.2% | 10.5% | 11.6% | 12.7% | 13.6% | 14.6% | ||
| Gross profit | 17,660.0 | 17,450.0 | 17,094.0 | 19,974.0 | 21,937.1 | 24,653.3 | 28,142.1 | 32,477.1 | 37,777.7 | |
| Gross margin | 18.2% | 17.9% | 18.0% | 19.3% | 19.2% | 19.3% | 19.5% | 19.9% | 20.1% | |
| EBITDA | 10,434.0 | 9,592.7 | 11,492.5 | 13,511.3 | 15,636.9 | 17,877.4 | 20,250.4 | |||
| EBITDA margin | 11.0% | 9.3% | 10.0% | 10.6% | 10.9% | 10.9% | 10.8% | |||
| EBIT | 8,891.0 | 7,076.0 | 4,355.0 | 3,466.0 | 3,692.0 | 4,285.0 | 5,196.0 | 6,402.0 | 7,894.1 | |
| EBIT margin | 9.2% | 7.2% | 4.6% | 3.3% | 3.2% | 3.4% | 3.6% | 3.9% | 4.2% | |
| Pre-tax income | 9,973.0 | 8,990.0 | 5,278.0 | 4,214.0 | 4,429.9 | 4,773.5 | 5,447.2 | 6,437.6 | 7,804.1 | |
| Income taxes | (5,001.0) | 1,837.0 | 1,423.0 | 935.0 | 982.9 | 1,059.1 | 1,208.6 | 1,428.4 | 1,731.6 | |
| Effective tax rate | (50.1%) | 20.4% | 27.0% | 22.2% | 22.2% | 22.2% | 22.2% | 22.2% | 22.2% | |
| Net income | 7,091.0 | 3,794.0 | 3,218.0 | 3,386.0 | 3,653.3 | 4,177.6 | 4,948.2 | 6,011.5 | ||
| Net margin | 7.3% | 4.0% | 3.1% | 3.0% | 2.9% | 2.9% | 3.0% | 3.2% | ||
| Cash flow | ||||||||||
| Cash flow from operations | 11,771.0 | 11,447.7 | 12,116.9 | 13,988.5 | 15,947.6 | 18,027.8 | 20,318.2 | |||
| Capex | 8,552.0 | 17,352.0 | 17,352.0 | 17,352.0 | 17,352.0 | 17,352.0 | 17,352.0 | |||
| Unlevered free cash flow | 1,630.8 | 130.6 | (5,748.2) | (3,682.6) | (1,538.9) | 709.1 | 3,097.3 | |||
| FCF margin | 1.7% | 0.1% | (5.0%) | (2.9%) | (1.1%) | 0.4% | 1.7% | |||
| Balance sheet | ||||||||||
| Cash and cash equivalents | 16,139.0 | 16,513.0 | 17,853.0 | 12,602.9 | 8,590.4 | 2,800.0 | 3,386.8 | 6,353.0 | ||
| Financial debt | 8,213.0 | 8,376.0 | 9,523.0 | 8,546.0 | 7,897.0 | 3,511.0 | 3,422.0 | 3,422.0 | ||
| Net debt (financial debt − cash) | (7,926.0) | (8,137.0) | (8,330.0) | (4,056.9) | (693.4) | 711.0 | 35.2 | (2,931.0) | ||
| Total equity | 73,680.0 | 82,865.0 | 89,889.0 | 93,275.0 | 96,928.3 | 101,105.9 | 106,054.1 | 112,065.6 | ||
| Balance check (assets − liabilities − equity) | - | - | - | - | - | - | - | - | ||
| Key ratios | ||||||||||
| EBITDA margin | 11.0% | 9.3% | 10.0% | 10.6% | 10.9% | 10.9% | 10.8% | |||
| ROIC (EBIT × (1 − t) ÷ average invested capital) | 8.7% | 4.6% | 3.5% | 3.4% | 3.6% | 4.1% | 4.8% | 5.7% | ||
| FCF margin | 1.7% | 0.1% | (5.0%) | (2.9%) | (1.1%) | 0.4% | 1.7% | |||
| Net debt ÷ EBITDA | (0.78x) | (0.87x) | (0.35x) | (0.05x) | 0.05x | 0.00x | (0.14x) | |||
| EBITDA ÷ interest | 30.87x | 27.57x | 39.72x | 53.53x | 67.11x | 175.66x | 204.33x | |||
| Minimum DSCR over the projection | (4.21x) | |||||||||
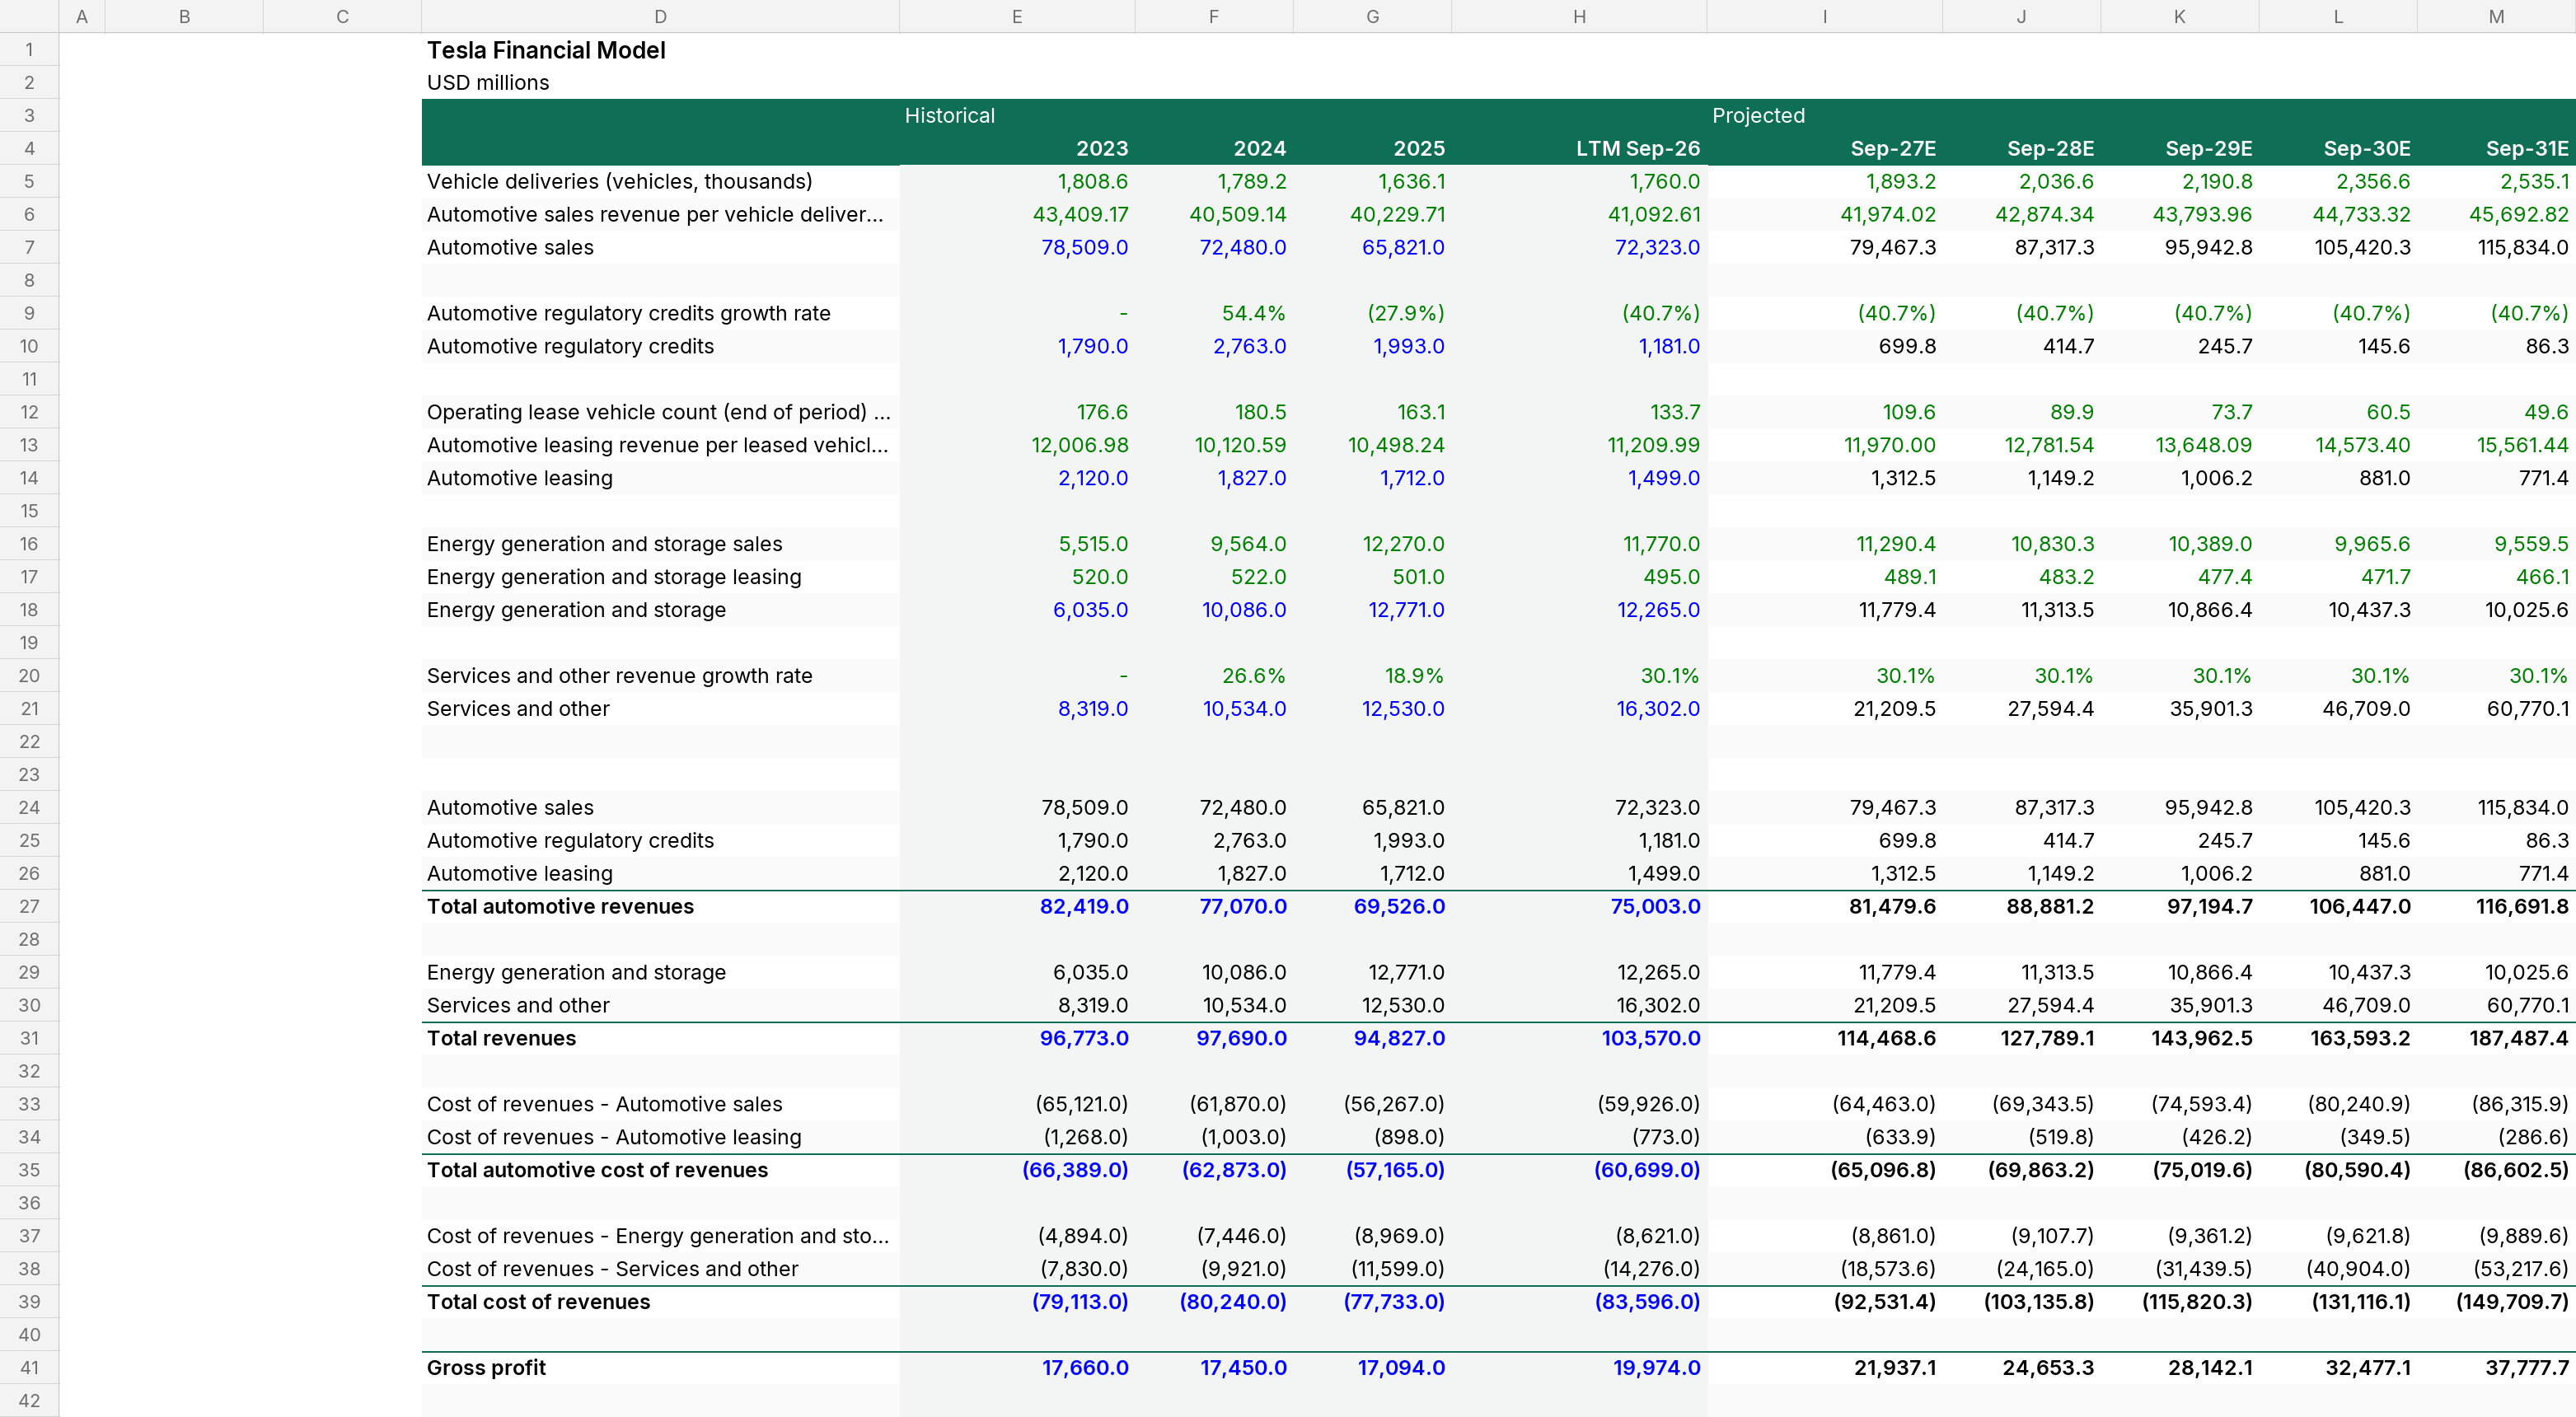
How revenue is built
Skale reads the documents to decide how each revenue stream is projected, and explains why.
Automotive sales are vehicles sold, and Tesla reports deliveries every year. Revenue = deliveries x average revenue per delivery. This is also how the MD&A explains the stream (cash deliveries and average selling price).
Credit revenue swings with regulation and buyer demand, and no credit volume is disclosed. The stream moved from 1,790 to 2,763 to 1,993 million and is falling in 2026, so it gets growth on the prior value with the growth rate held as an independent driver.
Leasing revenue is amortised over a lease fleet that Tesla reports. Revenue = lease fleet x revenue per leased vehicle.
Energy sales are mostly Megapack and Powerwall, and the MD&A explains revenue through deployments and average selling price. Revenue = GWh deployed x revenue per GWh.
The stream is small and flat (520, 522 and 501 million), and it already uses growth with the growth rate held. No better driver is disclosed.
The stream mixes used vehicles, maintenance, charging, insurance and parts, so no single reported driver measures its main activity. It has grown strongly (8.3, 10.5, 12.5 billion), so it gets growth on the prior value with the growth rate held.
Build this for your company
Upload your financial statements; Skale builds the model, and you review the assumptions.
Get startedNew to financial models? What is a financial model?